Banks Raise Lending Rates for Top Borrowers Despite CBN Cuts

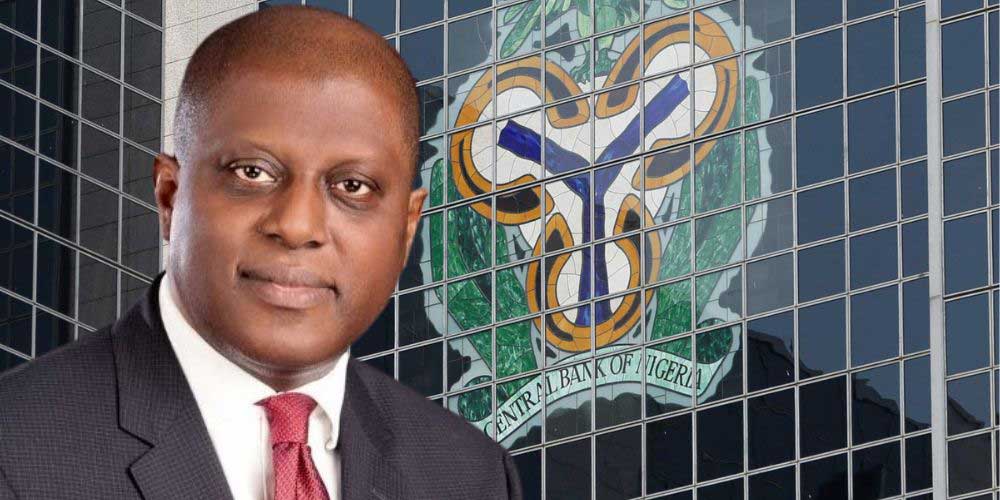
CBN Governor, Yemi Cardoso
BY FRONTLINE REPORTERS
Agriculture, construction, manufacturing face higher borrowing costs as analysts warn of delayed impact of monetary easing
Despite successive reductions in the Central Bank of Nigeria’s (CBN) Monetary Policy Rate (MPR), commercial banks have increased average prime lending rates in eight key sectors of the economy, raising concerns over the slow transmission of monetary easing to businesses.
Findings from the CBN’s published interest rate schedules for August 2025 and October 2026 show that average prime lending rates, which apply to creditworthy corporate borrowers, rose in agriculture, construction, government, healthcare, real estate, manufacturing, education, and finance and insurance. The increases ranged from 0.33 to 1.33 percentage points.
Agriculture, forestry and fishing recorded the highest increase, with prime lending rates rising to 24.77 per cent from 23.44 per cent. Construction increased to 26.40 per cent from 25.25 per cent, while manufacturing rose to 24.36 per cent from 23.79 per cent. Real estate, education and healthcare also recorded increases.
The development comes despite the CBN’s cumulative 450-basis-point reduction in the MPR over 13 months, from 27.5 per cent in September 2025 to 23 per cent in September 2026. The cuts followed a sustained moderation in inflation, which declined from 15.93 per cent in May to 14.63 per cent in September 2026.
However, average maximum lending rates declined across 10 sectors, falling to 32.58 per cent in October 2026 from 33.78 per cent in August 2025. Deposit rates also dropped, with average savings rates falling from 7.81 to 6.61 per cent and time-deposit rates declining from 14.52 to 12.28 per cent.
Commenting on the trend, Tunde Abioye, Head of Equity Research at Quest Merchant Bank, said the divergence between the MPR and sectoral prime lending rates did not necessarily indicate a breakdown in monetary policy transmission.
He explained that banks consider funding costs, liquidity conditions, borrowers’ risk profiles and other pricing factors when determining lending rates, adding that the data could reflect a delayed and uneven response to monetary easing.
Similarly, Nnamdi Nwizu, Co-Founder of Comercio Partners, said the increase in average prime lending rates was not widespread across the banking industry. According to his firm’s analysis of 174 comparable bank-sector observations, 65 recorded reductions, 79 remained unchanged, while only 30 registered increases.
The analysts warned that persistently high borrowing costs could discourage businesses from taking new loans, delay expansion projects and increase the cost of financing working capital. Agriculture and manufacturing could be particularly affected, given their dependence on affordable credit for raw materials, inventories, equipment and production.
They added that sustained high lending rates could weaken private investment, corporate profitability and employment creation, while constraining productive capacity and complicating efforts to achieve sustainable economic growth.
Nwizu, however, cautioned against concluding that the CBN’s easing measures had failed, noting that the 350-basis-point reduction announced on September 22, 2026, came just 17 days before the October lending-rate observation. He said the full impact of the policy adjustment would take time to reflect in banks’ lending rates, particularly as monetary easing tends to transmit more slowly than monetary tightening.
ADVERTISEMENTS: